Key Takeaways
- A bankruptcy trustee is appointed by the U.S. Trustee (a Department of Justice official), not the judge, to administer your case.
- A Chapter 7 trustee sells non-exempt property and pays creditors. A Chapter 13 trustee collects your plan payments and distributes them.
- The trustee is not neutral and not your lawyer. They act for the bankruptcy estate and creditors as a group, and cannot give you legal advice.
- You’ll meet the trustee once, at the 341 meeting of creditors, held by Zoom in Michigan. No judge attends.
- Chapter 7 trustee pay rises to a flat $120 per case for cases filed on or after October 1, 2026; a Chapter 13 trustee’s fee is capped at 10% of plan payments.
Between the moment you sign your bankruptcy petition and the moment the court closes your case, one person reviews your tax returns, questions you under oath, and decides whether anything you own gets sold to pay creditors. That person is the bankruptcy trustee.
They are not the judge. They are not your lawyer. And they do not work for you. They answer to the bankruptcy estate and to the creditors on your schedules. Here is exactly who appoints the bankruptcy trustee, what they do in Chapter 7 and Chapter 13 cases, and what the trustee cannot do, in Michigan.
Who Appoints the Bankruptcy Trustee?
A common point of confusion is worth clearing up: the court does not pick your trustee. In a Chapter 7 case, the U.S. Trustee appoints an impartial interim trustee from a panel of private trustees (11 U.S.C. § 701). In a Chapter 13 case, the U.S. Trustee appoints a standing trustee who handles every Chapter 13 case in an assigned area (§ 1302(a); 28 U.S.C. § 586(b)).[1] The bankruptcy judge stays out of day-to-day administration and only steps in to decide disputes.
What Does a Chapter 7 Trustee Do?
A Chapter 7 trustee’s core job is to turn your non-exempt property into money for creditors, and to make sure your paperwork is accurate. Their main duties are set out in 11 U.S.C. § 704.[2]
Reviewing Your Petition
The trustee checks your schedules, pay stubs, and tax returns against your assets and income, looking for anything missing or inaccurate. Most consumer Chapter 7 cases are “no-asset” cases, meaning there is nothing non-exempt to sell and creditors receive nothing.
Selling Non-Exempt Property
If you do own property that is not protected by an exemption, the trustee collects it, sells it, and distributes the proceeds to creditors under the priority rules of the Bankruptcy Code. Exempt property, the things you are allowed to keep for a fresh start, stays with you.
Objecting to Exemptions or Discharge
The trustee can object to exemptions you claim or, “if advisable,” oppose your discharge when there is a legal reason. The trustee can also undo certain pre-filing transfers (preferences and fraudulent transfers) to recover money for the estate. A judge, not the trustee, rules on any objection.
Running a Business With Court Approval
If your Chapter 7 includes a business, the trustee can operate it only when the court specifically authorizes it, and only for a limited period when doing so serves the estate’s interest (11 U.S.C. § 721). The trustee is not there to be your business consultant.[3]
What Does a Chapter 13 Trustee Do?
A Chapter 13 trustee oversees your repayment plan. The Chapter 13 trustee reviews the plan to confirm it meets the legal requirements, then acts as the disbursing agent: collecting your monthly plan payments and distributing them to creditors over three to five years (11 U.S.C. § 1302(b)). The Chapter 13 trustee is also required to help you with performance under the plan, but only on non-legal matters (§ 1302(b)(4)); the trustee does not give legal advice and does not represent you.
Chapter 7 vs. Chapter 13 Trustee
| Chapter 7 trustee | Chapter 13 trustee | |
|---|---|---|
| Appointed by | U.S. Trustee, from a panel (interim trustee) | U.S. Trustee (standing trustee for the area) |
| Main job | Sell non-exempt property, pay creditors | Collect and distribute monthly plan payments |
| You interact | Mainly once, at the 341 meeting | At the 341 meeting, then monthly through the plan |
| How paid | flat $120 per case (filed on/after Oct 1, 2026), plus a capped commission on funds paid out | A percentage of plan payments, capped at 10% |
What Happens at the 341 Meeting of Creditors?
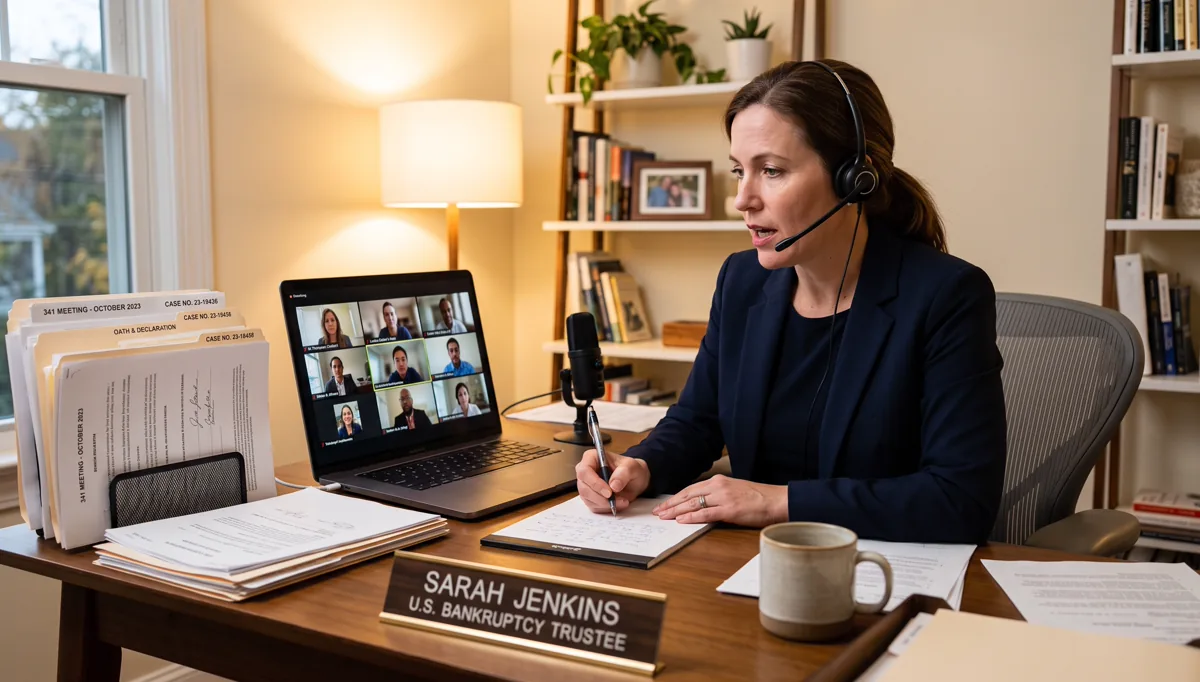
For most filers, the 341 meeting is where they meet the trustee in person. It is run by the trustee, under oath, and no judge attends (11 U.S.C. § 341). The trustee asks a short set of routine questions set by the U.S. Trustee Program, to confirm your identity and that your schedules, Statement of Financial Affairs, and tax returns are accurate and complete. Creditors may attend but usually do not.[4]
- Timing: generally 21–40 days after filing in Chapter 7, and 21–50 days in Chapter 13 (FRBP 2003(a)).
- Bring: a government photo ID and proof of your Social Security number (FRBP 4002(b)).
- In Michigan: the U.S. Trustee’s Region 9 holds these meetings by Zoom video conference, so most filers attend from home or their lawyer’s office.
What Questions Will the Trustee Ask?
The U.S. Trustee Program publishes a list of ten required statements and questions the trustee must cover with every Chapter 7 debtor at the 341 meeting. In plain English, the trustee will ask you to:
- State your name and confirm the address on your petition.
- Show your government photo ID and Social Security card for identity verification.
- Confirm that you signed and read the petition, schedules, Statement of Financial Affairs, and related documents.
- Confirm that you are personally familiar with the information in those documents, that it is true and correct, and that there are no errors or omissions to raise.
- Confirm that every asset you own is listed on the schedules and that every creditor is listed too.
- Say whether you have ever filed bankruptcy before.
- Give the address of your current employer.
- Confirm that the tax return copy you provided is a true copy of your most recent filed return.
- Say whether you owe a domestic support obligation, such as child support or alimony, and to whom.
- Confirm that you have read the Bankruptcy Information Sheet published by the U.S. Trustee.
Depending on your situation, the trustee may also follow up on real estate, recent transfers, bank accounts, lawsuits, inheritances, and vehicles, especially in cases where there may be non-exempt assets to administer.[5]
How Is a Bankruptcy Trustee Paid?
Trustees are not paid by you directly in the way a lawyer is. In Chapter 7, the trustee receives a flat per-case payment, which rises permanently to $120 for cases filed on or after October 1, 2026 (Bankruptcy Administration Improvement Act of 2025).[6] In an asset case, the trustee also earns a commission on money actually distributed to creditors, capped on a sliding scale by 11 U.S.C. § 326(a). In Chapter 13, the trustee is paid a percentage of the payments that flow through the plan, capped at 10% (28 U.S.C. § 586(e)).
What a Trustee Cannot Do for You
It is just as important to know the limits of the role. A trustee is not a neutral referee and is not your financial planner. They owe their duty to the bankruptcy estate and to creditors as a group, not to you. They cannot give you legal advice, cannot tell you which chapter to file, and do not decide disputes, that is the judge’s job. For advice on your own side, you need your own Michigan bankruptcy lawyer.
Working With a Trustee in Michigan
Michigan has two federal bankruptcy courts. The U.S. Bankruptcy Court for the Eastern District of Michigan has divisional offices in Detroit, Flint, and Bay City; the Western District covers the rest of the state. Which division handles your case depends on the Michigan county where you file.
Michigan also lets filers choose between state and federal exemption systems, which affects what a Chapter 7 trustee can reach. The exemption choices you and your attorney make before filing shape how much, if anything, the trustee administers.
In the Eastern District, five Chapter 13 standing trustees share the caseload:[7]
- Melissa A. Caouette (Flint)
- Krispen S. Carroll (Southfield)
- Thomas W. McDonald, Jr. (Saginaw)
- David W. Ruskin (Southfield)
- Tammy L. Terry (Detroit)
Which standing trustee is assigned to your case depends on the division where it is filed. For a walk-through of the full process, see our guide to the steps of Chapter 7 bankruptcy in Michigan.
Frego & Associates Offices Across Michigan
Frego has five offices to serve Michigan filers:
- Dearborn Heights:(313) 724-5088
- Warren:(586) 619-9432
- Ann Arbor / Ypsilanti:(734) 213-2599
- Flint:(810) 424-1614
- Saginaw:(989) 401-7700
Facing the 341 Meeting or Unsure About the Process?
Knowing what the trustee will and won’t do is half the battle, and you don’t have to walk into that meeting alone. Frego & Associates has guided Michigan families through bankruptcy for over 30 years, and the first conversation costs nothing.
Frequently Asked Questions
Do I Have to Meet the Bankruptcy Trustee?
Yes. You must attend the 341 meeting of creditors, where the trustee puts you under oath and asks routine questions about your paperwork and finances. It is usually short, and in Michigan it is held by Zoom. No judge attends, and in most cases creditors do not either.
What Questions Will the Trustee Ask at the 341 Meeting?
The U.S. Trustee Program publishes ten required questions used at every Chapter 7 341 meeting. They start with identity confirmation, then cover whether you signed, read, and personally reviewed the petition and schedules.
From there the trustee asks whether the information is true and complete, whether every asset and creditor is listed, prior bankruptcies, your current employer’s address, your most recent tax return, any child-support or alimony you owe, and whether you have read the U.S. Trustee’s Bankruptcy Information Sheet.
How Is a Bankruptcy Trustee Paid?
In Chapter 7, the trustee receives a flat per-case payment (rising to $120 for cases filed on or after October 1, 2026) plus a commission on any money distributed to creditors, capped by 11 U.S.C. § 326(a). In Chapter 13, the trustee is paid a percentage of your plan payments, capped at 10%. You do not pay the trustee directly the way you pay your attorney.
Can the Trustee Take My House or Car?
Only if there is non-exempt equity. A Chapter 7 trustee can sell property that is not protected by an exemption, but most consumer cases are “no-asset” cases where everything is exempt and nothing is sold. In Chapter 13, you keep your property and pay over time. Your exemption choices, made with your attorney before filing, decide what the trustee can reach.
Can a Bankruptcy Trustee Investigate My Financial Transactions?
Yes. A trustee can review your past transactions to identify fraudulent activity or preferential transfers that can be reversed to benefit creditors. They can examine your records, question you at the 341 meeting, and bring lawsuits to recover improperly transferred assets.
What Happens If the Trustee Suspects Fraud or Misconduct?
If a trustee suspects fraud, they can object to your discharge, refer the case to the U.S. Trustee Program for investigation, and file lawsuits to recover assets. Serious cases can be referred for criminal prosecution. Full, honest disclosure on your forms is always the safer path.
What Is the Difference Between a Chapter 7 and a Chapter 13 Trustee?
A Chapter 7 trustee liquidates non-exempt assets and distributes the proceeds to creditors. A Chapter 13 trustee oversees your repayment plan, collecting your monthly payments and distributing them to creditors over three to five years. Both are appointed by the U.S. Trustee, not the court.
Sources
All sources retrieved October 28, 2026.
- 11 U.S.C. § 701 (appointment of interim Chapter 7 trustee) and § 1302 (Chapter 13 trustee); 28 U.S.C. § 586 (U.S. Trustee appointment of standing trustees; 10% fee cap at § 586(e)). Legal Information Institute, Cornell Law School.
- 11 U.S.C. § 704 (duties of a Chapter 7 trustee). See also U.S. Courts, Chapter 7 Bankruptcy Basics.
- 11 U.S.C. § 721 (authority to operate the debtor’s business only with court authorization).
- 11 U.S.C. § 341 (meeting of creditors; no judge attends, § 341(c)); Fed. R. Bankr. P. 2003(a) (timing) and 4002(b) (identification). U.S. Trustee Region 9 (Michigan/Ohio) holds 341 meetings by Zoom.
- U.S. Trustee Program, “Section 341(a) Meeting of Creditors: Required Statements/Questions” (U.S. Department of Justice, Handbook for Chapter 7 Trustees, 2012).
- U.S. Courts, “Bankruptcy Administration Improvement Act Chapter 7 Trustee Payments”. BAIA 2025 (Pub. L. 119-76, signed Feb. 6, 2026): Chapter 7 trustee compensation permanently increases to $120 for cases filed on or after Oct. 1, 2026. Commission caps at 11 U.S.C. § 326(a).
- U.S. Trustee Program, Private Trustee Locator – Chapter 13 (U.S. Department of Justice), listing standing trustees Caouette (Flint), Carroll (Southfield), McDonald (Saginaw), Ruskin (Southfield), and Terry (Detroit) for the Eastern District of Michigan.
This article is general information about the role of a bankruptcy trustee, not legal advice, and reading it does not create an attorney-client relationship. Procedures and dollar amounts change; verify current details with a licensed attorney or the cited authorities.